Free crash course

Your First Cash Flow Plan

This crash course in cash flow planning shows you in six short chapters how to set up your first cash flow plan: no prior knowledge needed, with examples you can work through yourself. Read it right here – or get it as an eBook.

Your First Cash Flow Plan

You are not alone

Will the money last until the end of the month? If that question keeps you up at night now and then, you share it with a great many business owners. And the figures show: the worry is not exaggerated.

15 days

not even that long could half of all small businesses in the US have paid their running costs from their bank balance in 2020 if no more money had come in. Only 40 percent had more than three weeks of reserves. Five years earlier, the median business still had 27 days (JPMorgan Chase Institute).

23,900

that many companies filed for insolvency in Germany in 2025, more than at any time in over ten years. More than four out of five were micro-businesses with up to ten employees (Creditreform).

54 percent

of companies in Germany accepted longer payment terms last year (Intrum). Your customers' money arrives later, your bills still arrive on time.

More than one in four

medium-sized companies in Germany has an equity ratio below 10 percent (KfW). With so little cushion, there is not much room for surprises.

A few weeks of buffer, customers who pay later, an environment that is harder to predict than it used to be: it doesn't take a big crisis to get into trouble. A major customer who pays a month late is enough.

The good news: you don't have to guess. A cash flow plan shows you weeks in advance when things will get tight and buys you the time to act. If you know your low point, you talk to the bank before you have to, postpone spending before it is due and remind customers before the till runs dry. More figures and what they mean are in our eBook “From Plan to Payment”.

What this course is about

This crash course shows you in six short chapters how to set up your first cash flow plan: no prior knowledge, no jargon, with examples you can work through yourself. You don't need a degree or a finance department. You need your bank statements, a list of your open invoices and an hour of your time.

The course is for founders, managing directors of small and medium-sized companies and anyone who looks after the money in a business without being a finance professional. You can read it from start to finish or jump straight to the chapter you need right now. And if you only have two minutes: start with the ten rules of thumb at the end.

Along the way you will come across boxes. Each has a fixed job:

  • Tip – a practical move that saves you time or trouble.
  • !Watch out – a spot where many people trip up.
  • €Example – a calculation to follow, with round numbers.
  • Key term – a word you should know, explained in one sentence.
  • AIHow AI helps – what AI can take off your hands today. One rule always applies: the AI suggests, you approve.
01

Chapter 1

Why liquidity matters

In this chapter

  • why profit and money in the bank are two different things
  • how financial planning and cash flow planning differ
  • why small businesses need to be especially careful
  • what you cannot hand over as a managing director

Stable liquidity is the lifeline of every business. Without it, even a profitable company gets into trouble, and faster than many think. Because invoices, salaries and rent are not paid out of profit, but out of the bank account.

Key term

Liquidity means the ability to pay, at every point in time: you can pay your bills on the day they are due, not just on average over the month. Cash flow is the money that flows into your account in a given period, minus the money that flows out.

Profit is not money in the bank

The profit and loss statement and the cash flow plan pursue the same goal: a healthy business. But they look at different things. One asks whether you are earning money. The other asks when the money comes in and when it goes out.

€

Example

You win an order worth 50,000 euros. In May you pay 35,000 euros for materials and extra working hours. The invoice to the customer goes out at the end of May with 60 days' payment terms. On paper you have earned 15,000 euros. In your account, you are 35,000 euros short until the end of July. If you don't plan for that, the most successful order of the year turns into a cash squeeze.

That is exactly why the monthly report from your tax adviser is not enough. It shows whether you are making a profit. It doesn't show whether the money will last until the end of the month.

Financial planning and cash flow planning

This is the question we are asked most often: aren't they the same thing? No. Both plan the future, but with a different goal, on a different basis and by different rules.

Financial planning Cash flow planning
Comes from accounting the bank account
Target profit liquidity
Looks at a period every point in time
Rules statutory rules, taxes no statutory rules, management
Structure chart of accounts for the annual financial statements categories by your priorities
Amounts net gross
Counts from invoice or service period date of payment

Financial planning tells you whether your business pays off. Cash flow planning tells you whether you can pay every single day. You need both, but when it comes to whether the money will last, only the second one counts. That is what this course is about.

COMMITLY

How it works in COMMITLY

COMMITLY focuses on cash flow planning: from the bank account, gross, at the date of payment and structured by your priorities.

Why small businesses need to be especially careful

Nothing matters more to small and medium-sized companies than liquidity. A large corporation has credit lines, reserves and a treasury department. A small business often has only a few options in a squeeze: postpone a payment, max out the overdraft, put in private money. The earlier you see a shortfall coming, the more options you have.

Tip

Ask yourself once a month: how long could we last if, from today, no more money came in? The answer in days is called cash buffer days, and it is the most honest liquidity figure there is.

What you cannot hand over

Monitoring liquidity is not optional. If you neglect it, managing directors and owners face legal consequences. In Germany, for example, § 1 of the StaRUG (Act on the Stabilisation and Restructuring Framework for Businesses) requires the management of limited companies to continuously monitor developments that could threaten the company's existence and to take countermeasures.

!

Watch out

You can delegate the monitoring of liquidity, but not the responsibility. Whoever keeps the figures for you should be trained, have access to all the information they need and understand the business as a whole, not just the numbers. And you should take a look yourself regularly. Austria, Switzerland and other countries have their own rules, but the idea is the same. If in doubt, ask your tax or legal adviser.

Transparency is part of this: if you record the basis on which you made a decision, anyone can follow your reasoning. That protects you from misunderstandings within the team and from awkward questions if things go wrong.

AI

How AI helps

An AI can explain why your profit and your bank balance are drifting apart if it knows your bank transactions and your accounts. Pay attention to where you send your figures, though: bank data doesn't belong in any old chat window, but in a tool with clear rules on data protection and access.

02

Chapter 2

The basic formula

In this chapter

  • the one formula every cash flow plan is based on
  • why you plan gross
  • your first month, worked through
  • why the month-end balance is misleading

A cash flow plan sounds complicated. In fact you have known it for a long time: from your household budget, from checking your private account before a holiday. It rests on a single formula:

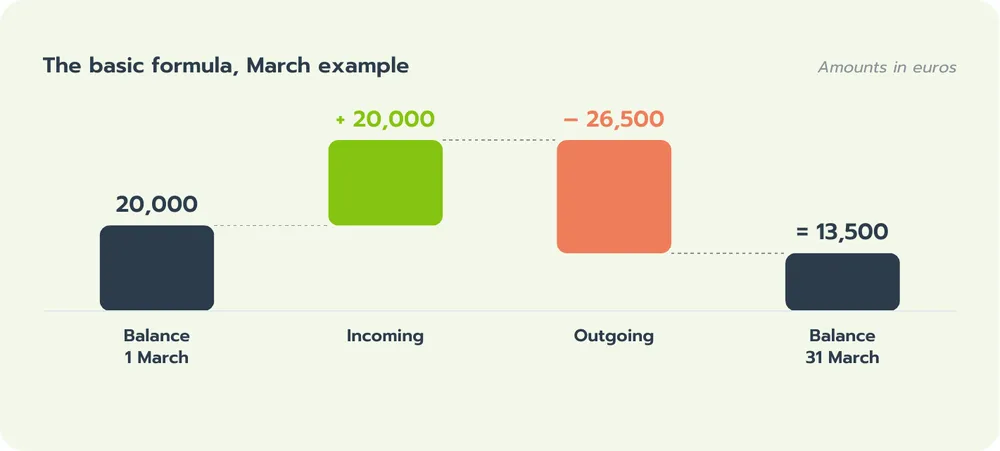
Today's balance + planned incoming payments − planned outgoing payments = tomorrow's balance

The basic formula: today's balance plus planned incoming payments minus planned outgoing payments equals tomorrow's balance

That's all there is to it. Everything that follows is about predicting the two middle figures, incoming and outgoing payments, as well as possible.

What the formula answers

Even this simple calculation helps you make better decisions:

  • Can we buy the new machine now, or do we wait two months?
  • Do we need to move money from the reserve account?
  • Can we hire someone in the autumn?
  • Will the overdraft be enough if the big customer pays late again?

In a business the process is the same as at home, just more extensive and more structured.

Plan gross, not net

Amounts arrive in your account including VAT and leave it including VAT. So your cash flow plan works with gross amounts, not net amounts like your accounts.

!

Watch out

The VAT is not yours. What you collect in VAT over the year you pass on to the tax office, minus input tax. So plan the VAT advance payment as a separate outgoing payment. It arrives on time and is often bigger than expected.

Your first month, worked through

€

Example

On 1 March there are 20,000 euros in the account.

  • Incoming in March: customer A pays 12,000 euros, customer B 8,000 euros. Together 20,000 euros.
  • Outgoing in March: salaries 15,000 euros, rent 3,000 euros, suppliers 6,000 euros, VAT advance payment 2,500 euros. Together 26,500 euros.

20,000 + 20,000 − 26,500 = 13,500 euros on 31 March. So the account falls by 6,500 euros, even though business is going well. If that goes on for two months, things get tight in May. Now is the right time to talk to customer B about a down payment, not in May.

Why the month-end balance is misleading

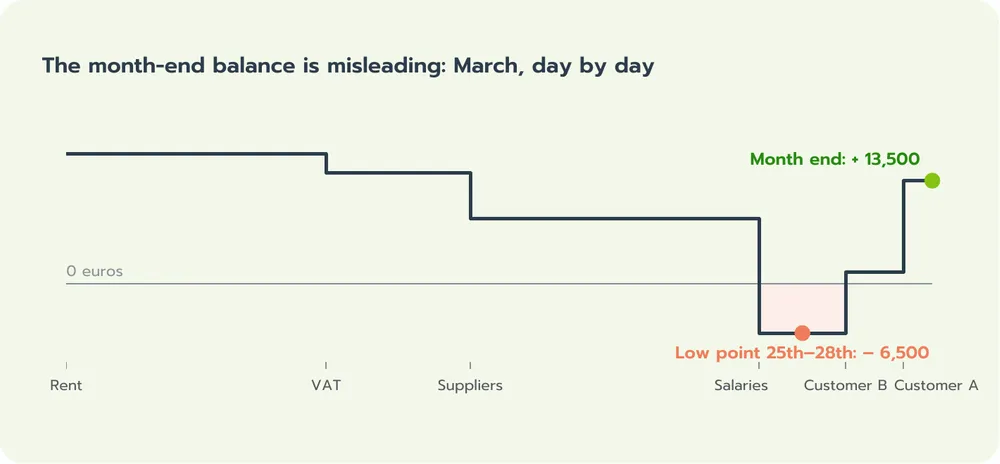
The 13,500 euros on 31 March don't mean that your account was in the black all month. It depends on the day the money moves. Suppose the rent goes out on the 1st, VAT on the 10th, the suppliers on the 15th and the salaries on the 25th. Customer B pays on the 28th, customer A on the 30th:

The month-end balance is misleading: bank balance in March day by day, 6,500 euros overdrawn from the 25th to the 28th, 13,500 euros in credit at month end

From the 25th to the 28th your account is 6,500 euros overdrawn, even though the month ends in the black. Without an overdraft facility, direct debits bounce on those days. A bar chart of month-end balances shows none of this.

!

Watch out

Look closely at the days with big payments: salaries, rent, VAT, social security contributions, loan instalments. They have fixed dates, your customers don't. For the next few weeks, plan by day or by week, not just by month.

That's all your first plan needs. Repeat the calculation for the next three to six months and you'll see where things are heading.

AI

How AI helps

An AI can create a first draft for the coming months from your bank transactions of the last few months: recognise recurring payments, carry seasonal patterns forward, flag outliers. You review the draft, adjust what you know better and approve it.

03

Chapter 3

What makes a good plan

In this chapter

  • the two qualities you can measure any plan against
  • three questions to check your plan
  • why the figures come from the bank account and not from the accounts

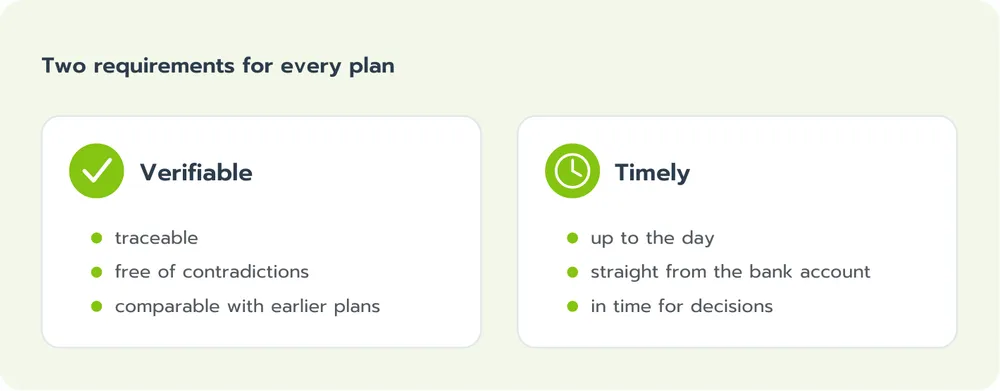
For all the pragmatism, a cash flow plan has to meet two requirements, otherwise it is no basis for decisions. It has to be verifiable and timely. That always applies, and in a crisis all the more.

Two requirements for every plan: verifiable and timely

Verifiable: can I trust the figures?

Verifiable means: the figures can be traced and are free of contradictions. Contradictions arise either in the figures themselves or in comparison with earlier plans. Three questions help you find them:

  1. Does the current plan match the previous ones?
  2. Were figures presented differently in the past?
  3. Where do the changes come from, and are they plausible?

Tip

Keep every plan you have shown to anyone: the bank, a shareholder, your team. Only then can you later compare what you expected with what actually happened. That is where you learn the most.

Timely: does the information arrive in time?

What good is the best information if it arrives too late? Many know the wait for the report from the tax adviser, which is already weeks old when it arrives. You can't plan with figures like that.

The current figures come straight from the bank account. There you see, up to the day, what has come in and what has gone out. A good cash flow plan starts right there.

Key term

Accounting records the past correctly and according to statutory rules, with receipts and to the cent. That matters, but for the question of whether the money will last until Friday it is too slow. The cash flow plan looks ahead and is allowed to round.

The link between the two worlds is the bank balance. Accounting and planning can always agree on that.

AI

How AI helps

An AI can hold your plan up against the actuals and point out contradictions: a budget that hasn't been met for months, an expense that suddenly goes missing, an assumption that doesn't fit your bank data. Which hints you take on board is your decision.

04

Chapter 4

Two perspectives: the operational planner and the long-term planner

In this chapter

  • two ways of looking at the future
  • what each does well and where it reaches its limits
  • why the best planning combines both

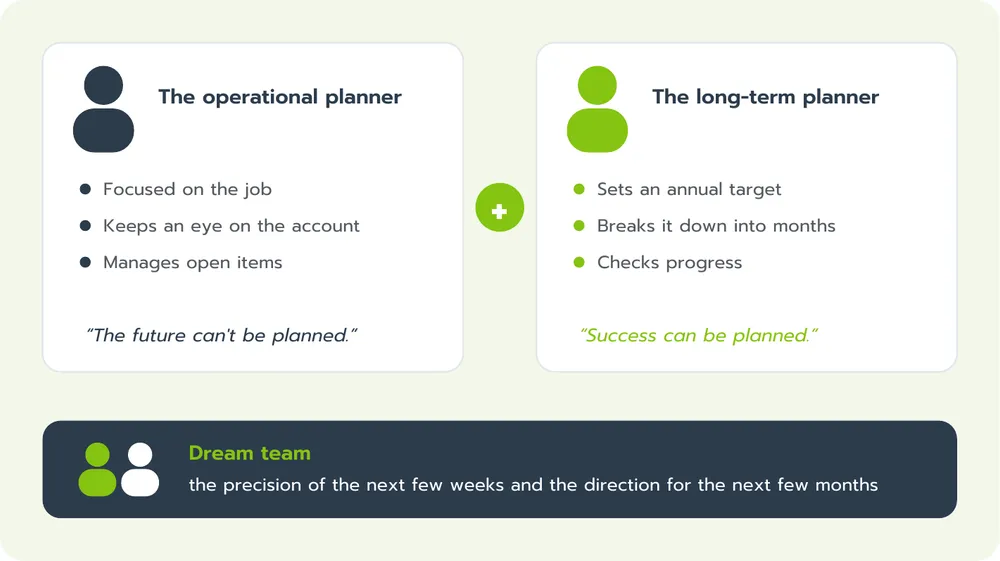
How someone plans has a lot to do with their job. In almost every company you meet two types, and both are right.

Two perspectives: the operational planner looks at the bank balance and open items, the long-term planner at annual targets

The operational planner

The operational planner is often also responsible for bookkeeping. They focus on their job, keep an eye on how the account develops and take care of the open items. Their attitude is understandable: in bookkeeping, no entry without a receipt, and every cent counts. Their motto: “The future can't be planned.”

How do you plan under these conditions? The only way out is the open items. They show the future incoming and outgoing payments on the account, as far as they are already known. For the next few weeks that is very precise. After that it gets thin.

The long-term planner

The long-term planner takes a different approach. They set an annual target, often driven by sales or growth goals, break it down into months and check whether they are on track. They don't calculate to the euro, but in thousands. That makes looking ahead much easier. Their motto: “Success can be planned.”

The dream team

Unsurprisingly, the best planning combines the strengths of both. The operational planner brings the precision of the next few weeks, the long-term planner the direction for the next few months. Together they see early whether the target is within reach, and in good time when things get tight.

Tip

If you combine both roles in one person, and in small businesses that is the rule: make separate time for both perspectives. Once a week the operational look at open items, once a month the long-term look at your targets.

05

Chapter 5

Short-term financial planning with open items

In this chapter

  • what open items tell you about your bank balance
  • how the plan and open items work together
  • where short-term planning ends and long-term planning begins

Short-term cash flow planning monitors and steers your payment flows and reserves over the next weeks to months. It helps you avoid shortfalls and is the basis for everything that follows. At its heart is managing your open items.

Key term

Open items are invoices that have been issued but not yet paid. Receivables are invoices to your customers that haven't been paid yet. Payables are your suppliers' invoices that you haven't paid yet.

What open items tell you

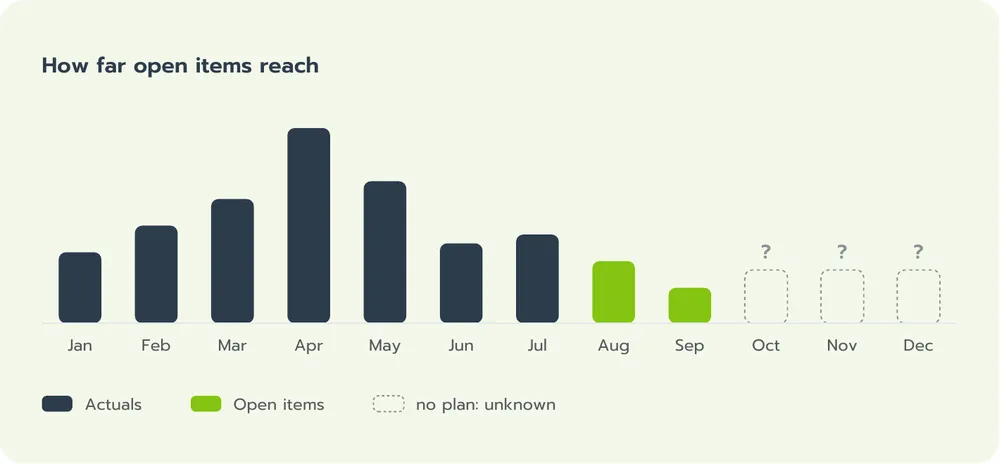
Open items show you which incoming and outgoing payments to expect over the coming weeks. That makes them the best indicator of how your bank balance will develop in the short term. The period in question is the payment terms: for most businesses the next two to eight weeks.

How far open items reach: actuals up to July, open items for August and September, after that unknown without a plan

If you keep your open items carefully, you spot trends early and can improve your cash flow in a targeted way: send reminders on time, negotiate payment terms, pay supplier invoices by due date rather than by date of receipt.

Tip

Sort your receivables once a week by due date and by amount. The three largest overdue invoices are almost always the quickest way to more money in the bank. A friendly phone call often works better than the third reminder.

Plan beats open items

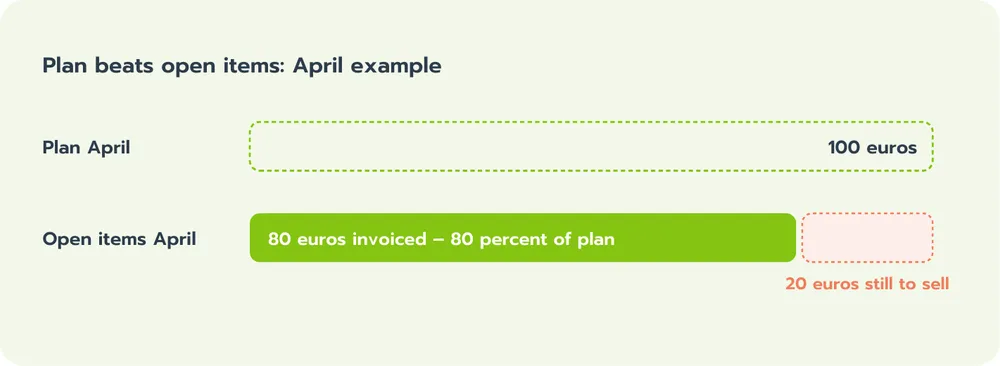
How do you bring the plan and open items together? The rule is simple: for every category and every month, either the planned figure applies or, if there isn't one, the total of the open items. If there is a plan, the open items show whether you are on track to reach it.

€

Example

For April you have planned 100 euros of incoming payments. Receivables due in April add up to 80 euros. That means 80 percent of your target has already been invoiced. Two tasks follow: make sure the 80 euros actually come in, and sell and invoice another 20 euros. If you hadn't planned anything for April, the forecast would show the 80 euros from the open items.

Open items show early whether the plan will be met

This rule has two advantages. You only plan what you want to plan, the rest comes from the open items. And you see early where action is needed, instead of getting lost in countless scenarios.

Short term and long term: two tasks

Short-term planning is geared to the immediate future. It needs flexibility in dealing with uncertainty: a customer pays late, a repair comes out of nowhere, and you have to react quickly. Long-term planning, by contrast, is preventive. It prepares the business for future challenges and aligns it with its goals.

In long-term planning, open items are less a basis than an indicator: of how your customers and suppliers pay and of how your cash flow develops. Both kinds of planning belong together. What you learn in the short term makes the long-term plan better.

!

Watch out

The room for manoeuvre with open items is small. An invoice that has already been issued can only be collected faster or slower. The real bottlenecks and opportunities show up three to nine months ahead. If you only look at open items, you see the shortfall when it is already there.

AI

How AI helps

A customer writes that they will only pay the invoice at the end of November. Instead of changing the date by hand, you forward the email to your AI: “Adjust the expected payment date and show me what that means for our low point.” The change comes in as a suggestion, and you approve it.

06

Chapter 6

Your first plan in five steps

In this chapter

  • how to build your plan for the medium and long term
  • why you lock a plan and still stay flexible
  • what the bank wants to see

Open items carry you a few weeks. For everything beyond that you need a plan. Here is how to build it.

Step 1: Connect accounts and set up categories

Connect all business accounts to your planning tool so that the actual figures arrive automatically and are up to date every day. Then set up the categories you want to plan by.

Structure them by your company's priorities, not by the accounts: by the customers, projects or products that carry your business, and by the spending you want to steer deliberately, such as staff, marketing, purchasing. Then your plan answers your questions and not those of the tax office.

Tip

Less is more. Ten to fifteen categories are enough to start with. A category you never look at is one nobody needs.

Step 2: The past as a starting point

Look at your bank transactions from the last six to twelve months. They show roughly where your incoming and outgoing payments lie, which payments recur and where there are seasonal patterns. On top of that you add what will be different in the future.

!

Watch out

The past is a starting point, not a forecast. Just because your business follows a pattern year after year doesn't mean it will repeat itself automatically. Check every large item to see whether it stays that way.

Step 3: The big items first

Start with the expenses you know well: salaries, rent, insurance, leasing, tax advice. They usually make up the largest share and are easy to predict. Then the income: don't plan revenue, plan incoming payments, that is, with your customers' payment terms and with bad debts.

Stick to the 80/20 rule: a few large items decide your liquidity. The less time you spend on small amounts, the more time you have for the questions that matter.

Key term

The forecast is your current expectation: actual figures as far as they are available, and your best estimate for the future. The forecast changes all the time. The plan, on the other hand, is a snapshot you lock at a point in time, for example for the financial year.

Keep what belongs to day-to-day business separate from investment and financing. A loan is not revenue, and a new machine is not a running cost. If you keep them apart, you see whether your day-to-day business pays for itself.

Step 4: Lock the plan

Once you are happy with your plan, you lock it. A locked plan can no longer be changed. That sounds rigid, but it is the whole point: it is the basis for every comparison of plan and actuals and for every conversation with the bank, investors or shareholders. Because nothing changes any more, you are always on the same page.

COMMITLY

How it works in COMMITLY

In COMMITLY, locking a plan is called “committing”. The committed plan stays unchanged and is the basis for plan-actual comparisons and reports. At the same time it becomes the new forecast, which you then keep updating.

If the bank wants to see a plan, for example for an overdraft or an investment loan, this locked version is exactly what you hand over. Which reports banks want to see is described in our article Which reports banks want to see.

Step 5: Compare and roll forward

The future rarely turns out as planned. An expected payment doesn't arrive, an order comes in earlier. Then you adjust the forecast, not the locked plan. That way you keep both: the current view ahead and the comparison with what you originally expected.

With every deviation, ask: is it a real deviation or just a shift in timing? Is the money not coming at all, or just later? Shifts are carried forward into the following months. No amount may get lost along the way.

€

Example

June was planned with 10,000 euros of incoming payments, 8,000 euros arrived. Sales says the missing 2,000 euros will come in July. Then they belong in the July forecast. The same applies to expenses, even more strictly: a planned expense that didn't occur in June will probably come later. If it disappears for good, you have gained a small buffer.

If the forecast and the plan drift too far apart, or the bank wants an updated version, you turn the current forecast into a new plan, agree on it and lock it again. Then the cycle starts over. This is called rolling planning: each month that has passed is replaced by the actual figures, the current bank balance becomes the new starting point, and the forecast calculates onward from there. That keeps the forecast as accurate as possible. The locked plan stays alongside it as the yardstick.

Tip

For the next few weeks, the week has proven itself as the unit: the next 13 weeks week by week, then month by month. That way you see the low point of your bank balance before you reach it.

Running the numbers on new projects

If you are planning an investment, a new location or a new product, run it as a scenario based on your forecast. That way you see how much capital the project needs, when the low point comes and whether you need a loan or funding. And you see it before you sign.

AI

How AI helps

Two tasks AI already handles well today. It assigns your bank transactions to categories and suggests rules for future bookings. And it runs scenarios: “Assume our largest customer pays two months later and show me the low point.” Both come in as a suggestion or a draft, and you have to approve them.

Finally

Ten rules of thumb for your first cash flow plan

  1. 1Get started. A rough plan today is worth more than a perfect plan next month.
  2. 2Plan from the bank account. The bank balance is the truth, everything else is expectation.
  3. 3Plan gross. And don't forget the VAT advance payment.
  4. 4Plan incoming payments, not revenue. Your customers' payment terms belong in the plan.
  5. 5Big items first. Ten items decide, a hundred just keep you busy.
  6. 6Structure by your priorities. Not by the report from your tax adviser.
  7. 7Use open items for the next few weeks. For everything beyond that you need a plan.
  8. 8Lock the plan and adjust the forecast. That way you can compare at any time.
  9. 9No amount gets lost. What didn't come will come later or not at all, and you decide which, deliberately.
  10. 10Check in every week. Ten minutes a week are enough, as long as you spend them every week.

For reference

Short glossary

Burn rate
how much more money your business spends per month than comes in. Important above all in the start-up and build-up phase. Also called cash burn.
Cash buffer days
how many days you could pay your running costs from your bank balance if, from today, no more money came in.
Cash flow
the money that flows into your account in a given period, minus the money that flows out. Positive means more comes in than goes out.
Forecast
your current expectation: actual figures as far as they are available, and your best estimate for the future. The forecast changes all the time.
Liquidity
the ability to pay, at every point in time: you can pay your bills on the day they are due. A positive balance at month end is not enough.
Open items
invoices that have been issued but not yet paid: to your customers (receivables) and from your suppliers (payables).
Overdraft
the credit line on your business account. Flexible, but usually expensive. It belongs in the plan as a reserve, not as a permanent state.
Payment terms
the period by which an invoice has to be paid, for example 30 days. Long payment terms for your customers cost you liquidity.
Plan
a snapshot you lock at a point in time, for example for the financial year or for the bank. It stays unchanged and is the yardstick for comparing plan and actuals.
Rolling planning
periods that have passed are continuously replaced by the actual figures. The current bank balance becomes the new starting point, and the forecast calculates onward from there. The result is a rolling forecast that is always as accurate as possible.
Runway
how many months your money will last at a constant burn rate: bank balance divided by burn rate. 60,000 euros in the account and 15,000 euros of burn per month make four months. Cash buffer days are the stricter calculation: they leave out every incoming payment.
Free eBook

The crash course as an eBook

All six chapters on 32 pages in a handy book format, with graphics, examples, ten rules of thumb and a short glossary. Sign up – we'll email you the download link.

  • The basic formula with an example to work through
  • Short-term financial planning with open items
  • Your first plan in five steps
  • Ten rules of thumb for your first cash flow plan

By signing up you will also receive our newsletter. You can unsubscribe at any time.

The crash course as an eBook

Questions about cash flow planning

A cash flow plan shows how your bank balance will develop over the coming weeks and months. The basic formula is: today's balance plus planned incoming payments minus planned outgoing payments equals tomorrow's balance. That way you see shortfalls before they happen.

Ready for your cash flow platform?